This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
Global financial markets closed a volatile week digesting a severe downside surprise in the U.S. labor market. Headline September Nonfarm Payrolls badly missed expectations, printing at just +29,000 against consensus estimates of 84,000–90,000. Compounding the weakness, July and August payrolls were revised down by a combined 60,000, while the unemployment rate ticked up to 4.2%.
Softening Labor Market: U.S. wage growth slowed to its weakest pace since May 2021, creating a cost-of-living squeeze as gas, diesel, and airfare prices continue to outrun paychecks.
Fed Hike Odds Collapse: The labor market cooling heavily diluted monetary tightening bets, with October Fed rate-hike probabilities collapsing to below 25% following the jobs release.
Yields Diverge on Deficit Concerns: Despite falling rate-hike odds, U.S. Treasury yields continued to climb higher, driven by persistent U.S. fiscal deficit concerns and elevated energy costs.
Following the collapse in October rate-hike bets alongside rising yields, Wednesday’s U.S. 10-year Treasury auction and FOMC meeting minutes will provide simultaneous tests of bond demand and the Fed’s stance on monetary policy.
Market participants will inspect the minutes for hawkish dissent or guidance on the inflation outlook following September’s rate hike.
2. ECB Policy Meeting Accounts — Thursday
Thursday’s ECB meeting accounts will reveal policymakers’ internal debate regarding further rate hikes. The ECB previously raised rates by 25 basis points as surging energy prices heightened Eurozone inflation risks. If the accounts reveal broad support for continued tightening, money markets could price in additional rate hikes, bolstering the Euro and European sovereign bond yields.
3. Canada September Employment Report — Friday
Friday’s Canadian employment report will test whether economic momentum can be sustained. Employment contracted by 42,000 in August while inflation held at 3.0%, placing the Bank of Canada in a stagflationary dilemma between slowing growth and elevated prices. Another weak jobs print could erase remaining rate-hike expectations and pressure the Canadian Dollar.
4. Middle East Escalation & Strait of Hormuz Standoff
Diplomatic optimism following the UN General Assembly has turned sour as Middle East conflicts escalate significantly:
Escalating Hostilities: Fighting in Yemen has intensified, with Houthi forces claiming a direct strike on a Saudi Arabia’s facility.
Strait Remains Closed: Iran stated it is fully prepared for a potential U.S. strike, asserting the Strait of Hormuz will remain closed until its seven diplomatic conditions are satisfied.
U.S. Military Reinforcements: Washington has reinforced Saudi Arabia and Qatar with additional Patriot missile defense systems to prepare for potential regional escalation, keeping energy traders on high alert.
U.S. Dollar Index: Mixed Forces Clash Near 102.00 Pivot
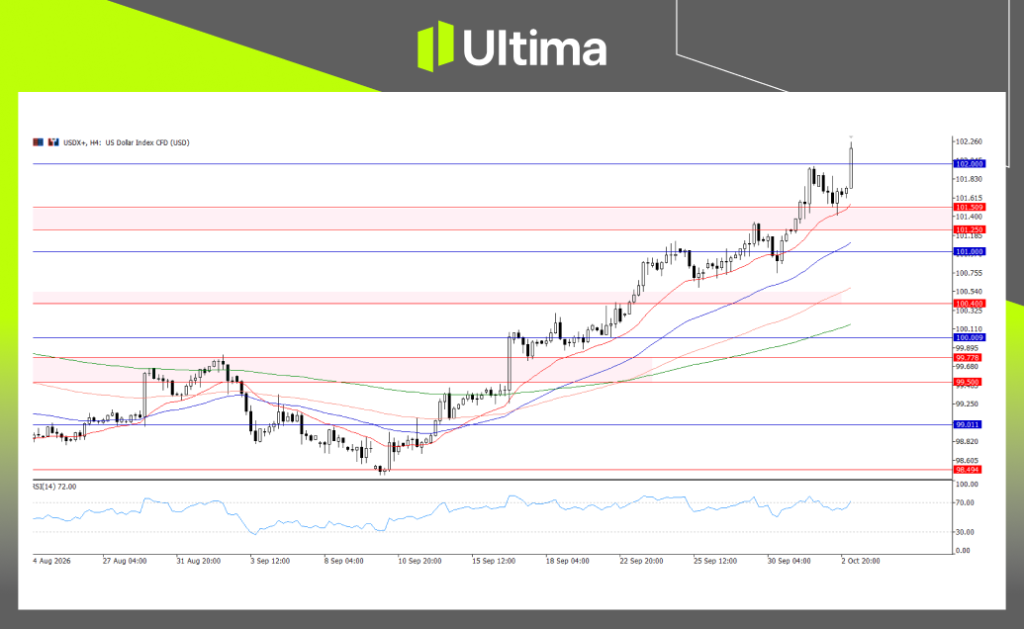
The U.S. Dollar continues to trade at elevated levels near the 102.00 pivot. While remaining structurally bullish, the Greenback faces a tug-of-war between dovish Fed rate-hike repricing (bearish) and rising long-term U.S. Treasury yields (bullish).
USDX, H4 Chart | Ultima Markets MT5
Technically, the Dollar Index continues to test the critical 102.00 structural pivot zone and holds solid on its bullish structure after testing strong support near 101.50 earlier last week.
With USDX now edging above 102.00, the bullish bias remains intact, favoring a buy-on-dips approach. However, if dovish Fed expectations trigger a technical pullback below 102.00, USDX risks a deeper corrective move back toward 101.00 support.
Until further price action confirms a breakdown, traders should maintain a cautious bullish stance while watching for overbought pullback signals.
Spot Gold: Capped in $4,100 – $4,200 Range as Yields Weigh
Gold prices remain trapped within a defined range, as safe-haven demand from Middle East friction is countered by rising real Treasury yields.
The outlook for Gold this week remains a technical watch as traders observe how the Dollar plays out.
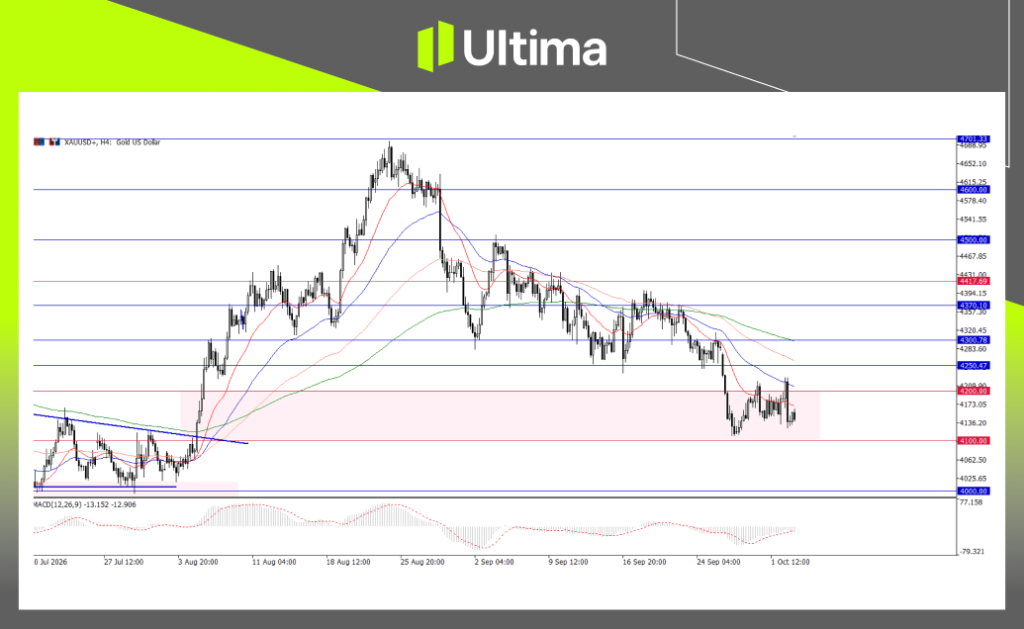
XAUUSD, H4 Chart | Ultima Markets MT5
Technically, Gold is bound between $4,100 and $4,200, with the current range acting as a crucial technical checkpoint. Rising Treasury yields continue to cap upside attempts near $4,200, while safe-haven demand and key technical support keep Gold supported near $4,100.
A decisive breakout above $4,200 is required to open the door for a bullish recovery toward $4,250.
Conversely, a breakdown below $4,100 would expose Gold to deeper downside risks toward $4,020.
Hence, for Gold traders, the near-term bias leans cautiously bearish while awaiting a clear technical breakout.
Crude oil prices are seeing renewed upward pressure as Middle East supply disruptions and Strait of Hormuz closures inject geopolitical risk premiums back into energy markets.
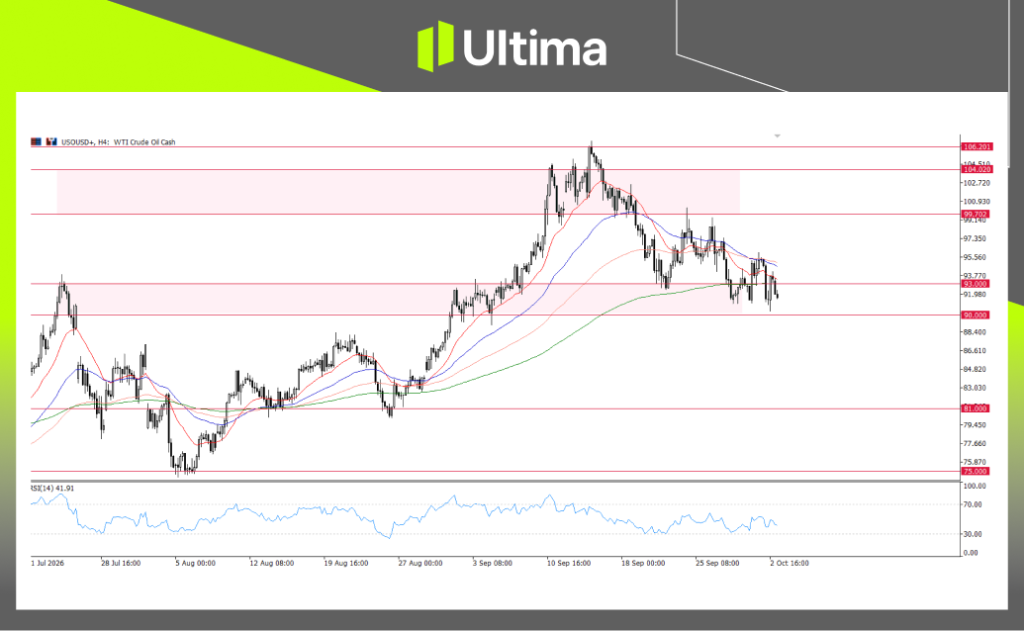
USOUSD, H4 Chart | Ultima Markets MT5
Technically, WTI Crude Oil (USOUSD) is defending key support around $90.00 to $94.00, with buyers eyeing overhead resistance at $99.50. As long as prices hold above $94.00, headline risks surrounding Aramco facilities and the Strait of Hormuz favor upside retests toward $99.50.
On a side note, WTI Crude has faced localized pressure while UKOUSD (Brent) traded flat-to-higher, holding firm above $105/bbl. This divergence has stretched the WTI-Brent spread to a rare high near $12/bbl.
The core driver behind this divergence stems from a tug-of-war between policy and geopolitical risks: U.S. Strategic Petroleum Reserve (SPR) releases have exerted direct downward pressure on WTI, whereas Middle East geopolitical risk premiums continue to provide strong structural support for Brent Crude.
Technically, unless a breakdown below $94.00 triggers a deeper pullback in USOUSD, sustained support at this level will likely keep both crude benchmarks trading at elevated levels over the near term.
Weekly Market Summary & Key Highlights
This week’s macro landscape will be defined by bond market demand, central bank guidance, rising long-term yields, and heightened geopolitical risk premiums across energy markets.
Simply put, traders should watch whether the U.S. Dollar holds its bullish structure above 102.00 post-FOMC minutes, if Gold can break out of its $4,100 – $4,200 range, and how the WTI-Brent spread evolves as Strait of Hormuz developments unfold.
What to Watch This Week:
US 10-Yr Auction & FOMC Minutes (Wednesday): Assess bond market demand and the Fed’s stance on inflation following the NFP miss.
ECB Meeting Accounts (Thursday): Gauge policymaker support for further rate hikes to determine Euro momentum.
Canada Employment Report (Friday): Track job growth to see if Bank of Canada rate-hike expectations soften further.
U.S. Dollar Index Pivot (102.00): Watch whether USDX holds 102.00 to target 102.80 or pulls back toward 101.00.
Spot Gold Range ($4,100 – $4,200): Monitor whether rising yields cap Gold below $4,200 or if a breakdown exposes $4,020.
WTI & Brent Crude Dynamics ($94.00 Support / $12 Spread): Track Strait of Hormuz headlines for WTI retests of $99.50 while watching the wide WTI-Brent spread.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.