This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
US Inflation & Q3 Earnings Season Take Center Stage
US Inflation & Q3 Earnings Season Take Center Stage
Ultima Markets Weekly Market Outlook & Insights – 12 to 16 October 2026
Wall Street Rebounds Ahead of Q3 Earnings & Inflation Test
Global financial markets enter the new trading week on a constructive note, buoyed by Wall Street’s Friday rebound following a brief wobble in AI-related tech stocks. As risk sentiment stabilizes, market attention shifts toward the official kickoff of the Q3 corporate earnings season, led by major U.S. banks.
On the monetary policy front, the Federal Reserve raised interest rates by 25 basis points in September to a target range of 3.75%–4.00%. However, September Nonfarm Payrolls printed at a sluggish +29,000 while the unemployment rate ticked up to 4.2%. This significant labor market cooling prompted money markets to sharply scale back expectations for an additional rate hike in October, shifting the macro spotlight directly onto this week’s U.S. inflation data and Q3 corporate earnings reports.
Week Ahead: Key Macro Outlook & Corporate Earnings
1. U.S. September CPI (Wednesday) & PPI / Retail Sales (Thursday)
Wednesday’s U.S. Consumer Price Index (CPI) report will provide a critical test of whether inflationary pressures remain persistent enough to offset recent labor market softening. With August CPI running at 3.4% year-on-year, only a materially higher-than-expected inflation reading is likely to revive near-term Fed rate-hike bets and push Treasury yields and the Greenback higher.
Thursday’s Producer Price Index (PPI) and Retail Sales reports will offer further clarity on wholesale price trends and domestic consumer demand. Following August’s 0.4% MoM PPI rise and 1.2% Retail Sales gain, stronger-than-expected figures could encourage markets to rebuild expectations for a late-2026 Fed rate hike. Conversely, softer readings would reinforce the central bank policy-pause narrative.
2. Q3 Corporate Earnings — Big Banks & TSMC
The third-quarter earnings season takes spotlight this week, serving as a primary driver for equity market direction:
Tech & Semiconductors: Taiwan Semiconductor Manufacturing Co. (TSMC) reports earnings on Thursday, testing whether global AI demand and advanced-node chip orders can sustain the broader semiconductor cycle. TSMC previously guided Q3 revenue between $44.6 billion and $45.8 billion; investors will focus closely on forward revenue guidance, gross margins, and AI capital expenditure trends.
Financial Sector: Major Wall Street banking institutions report quarterly results throughout the week, offering crucial insight into net interest margins, loan loss provisions, and overall domestic credit health.
3. Central Bank Officials’ Speeches
Key policymakers from the Federal Reserve, Bank of England (BoE), Reserve Bank of Australia (RBA), and European Central Bank (ECB) are scheduled to deliver remarks throughout the week. While unlikely to eclipse CPI and PPI data as direct market movers, traders will scrutinize these speeches for forward-guidance clues regarding post-September policy trajectories.
Weekly Technical Outlook: Dollar, Gold & US Equities
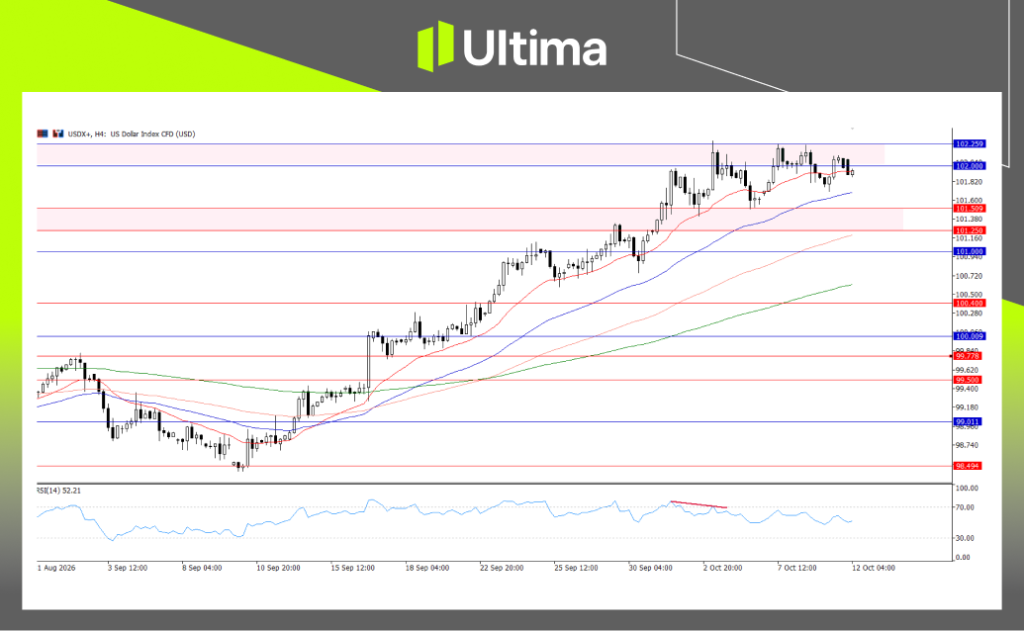
U.S. Dollar Index: Holding Near 102.00 Pivot as Overbought Conditions Persist
The Greenback continues to trade near 18-month highs, maintaining its broader structural bullishness above key support while facing near-term technical overhead resistance.
USDX, H4 Chart | Ultima Markets MT5
Technically, the Dollar Index is holding firm in the 102.00 – 102.10 resistance zone, with its broader bullish structure intact above 101.25.
However, after an extended multi-week rally without a significant technical correction, USDX faces overbought risk and could undergo a pullback unless Wednesday’s CPI print surprises significantly to the upside.
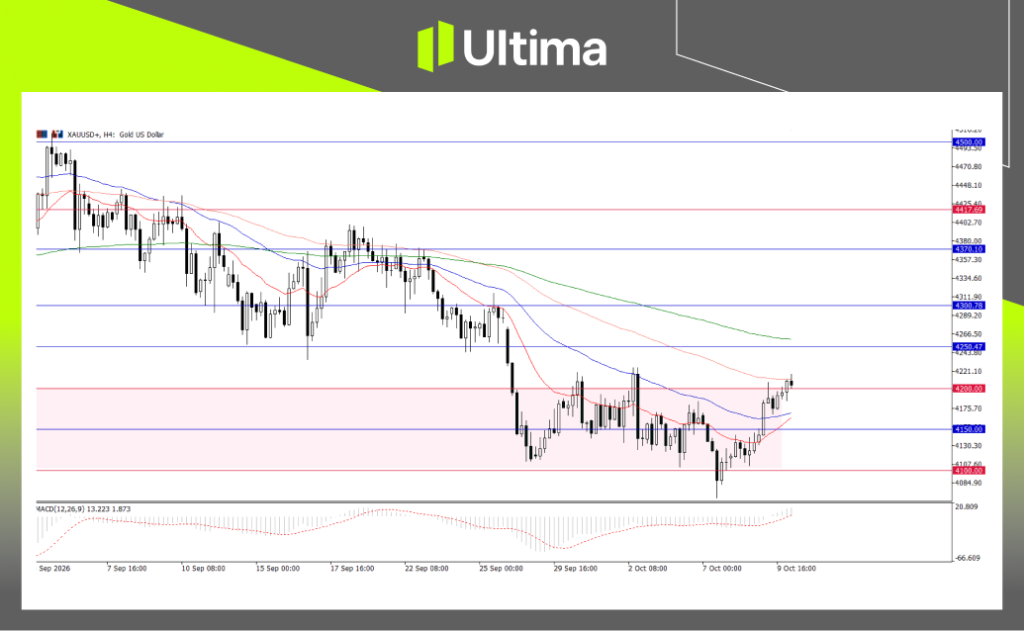
Spot Gold: Defending $4,150 Pivot Within $4,100 – $4,200 Range
Gold prices have stabilized following a temporary dip below $4,100, mounting a recovery back toward $4,194 and keeping the broader consolidation structure intact.
XAUUSD, H4 Chart | Ultima Markets MT5
Technically, Gold remains bound within a $4,100 – $4,200 trading range. The $4,150 level serves as the immediate structural pivot to hold for buyers. A decisive, sustained break above $4,200 is required to confirm a broader bullish recovery, while a breakdown below $4,150 would re-expose lower range support near $4,100.
U.S. Equities (S&P 500 & Nasdaq 100): Testing Record Highs Ahead of Earnings Gate
U.S. equity benchmarks remain firmly bullish, hovering near all-time high territory as the Q3 earnings season begins.
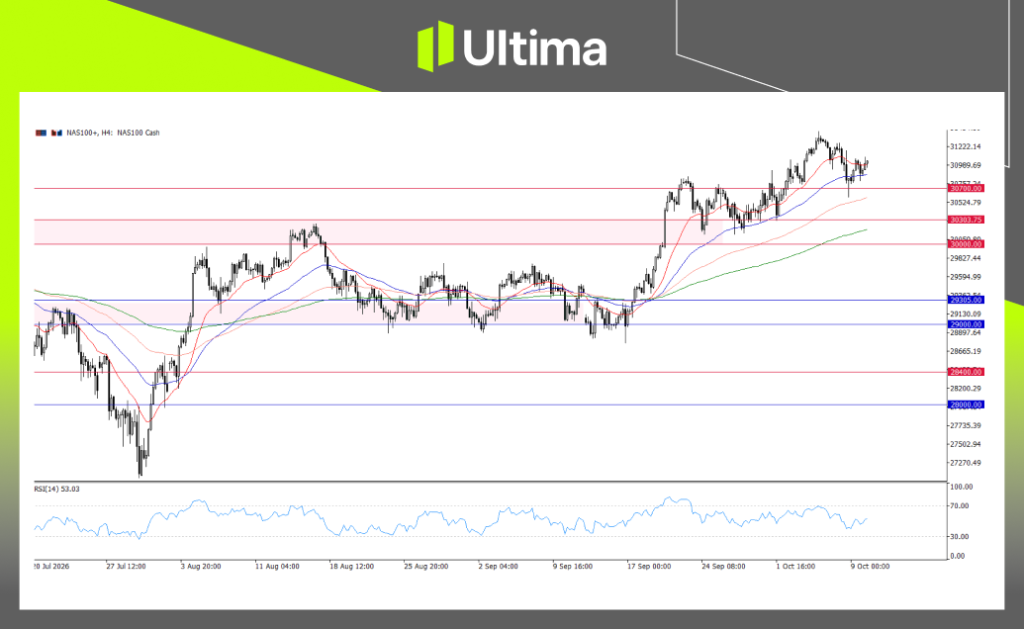
NAS100, H4 Chart | Ultima Markets MT5
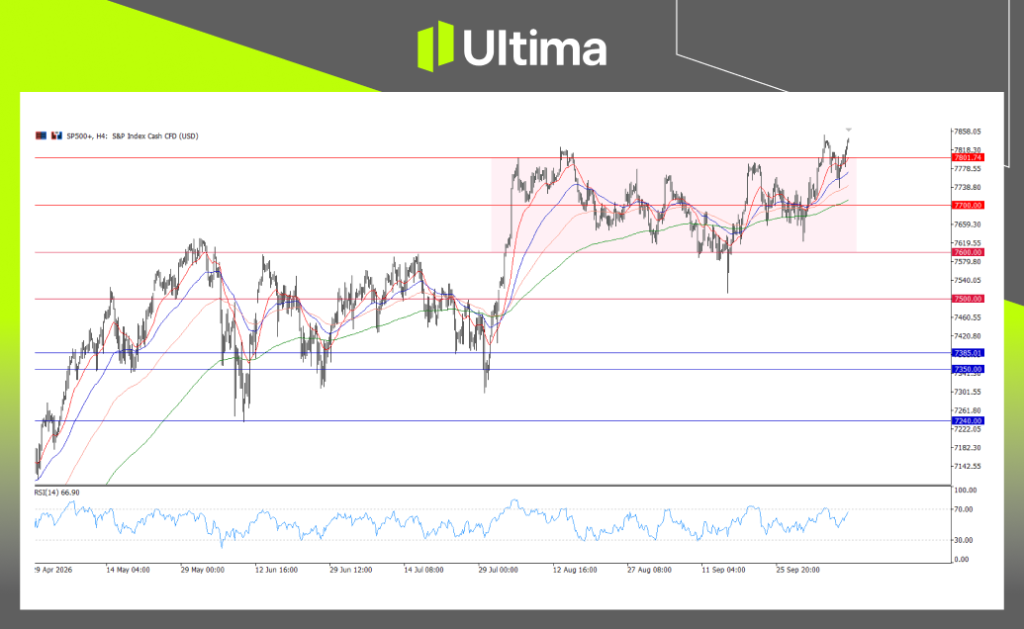
SP500, H4 Chart | Ultima Markets MT5
Technically, both the S&P 500 and Nasdaq 100 maintain positive momentum following Friday’s tech rebound.
For the S&P 500, structural support lies at 7,800.
For the Nasdaq 100, core technical support remains firm at 30,700.
As long as these support floors hold on pullbacks, the broader technical bias remains tilted to the upside, though corporate earnings guidance will dictate whether benchmarks can break out to fresh records.
Weekly Market Summary & Key Highlights
This week’s market trajectory will be dictated by a dual focus: macro inflation data determining Fed rate expectations, and Q3 corporate earnings driving equity market momentum.
Simply put, traders should watch whether U.S. CPI/PPI data provides fresh catalyst for the Dollar to break above 102.10 or triggers a corrective pullback, while monitoring if TSMC and big bank earnings can sustain the broader stock market rally above key support levels.
What to Watch This Week:
U.S. CPI & PPI Reports (Wednesday & Thursday): Monitor inflation data to see if Fed rate-hike expectations re-emerge or if policy-pause bets are solidified.
Q3 Corporate Earnings (TSMC & Big Banks): Track TSMC’s AI revenue guidance and major bank earnings to gauge equity market sustainability.
U.S. Dollar Index Resistance (102.00 – 102.10): Observe whether USDX breaks above 102.10 or pulls back toward support at 101.25.
Spot Gold Range ($4,100 – $4,200): Watch whether Gold holds above $4,150 to challenge $4,200 resistance or retests $4,100.
U.S. Equity Benchmarks (S&P 500 7,800 / Nasdaq 100 30,700): Track key support floors as major corporate earnings reports land.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.